This page explains Texas law in plain English and is not legal advice. We are roofers. In a dispute, or near a deadline, talk to a lawyer.
The short answer, in five steps
Two clocks matter and people confuse them: the notice provision in your policy, and the legal deadline to sue your carrier. Order matters too — document the roof before deciding whether a claim is worth filing.
- Get the roof inspected and documented. Dated photographs of every slope, the vents, the flashing and the gutters. Our inspector is HAAG-certified — the damage-assessment training the insurance industry uses — and we climb every roof we can safely walk.
- Read your declarations page: the notice provision, the wind and hail deductible, replacement cost versus actual cash value.
- File with your carrier yourself. You, the policyholder. Not us.
- Meet the adjuster on the roof with your photo report. We will be there too if you invite us.
- Build to the approved scope, and supplement if it comes back short — with a document, not an argument.
How to know whether you have a claim at all
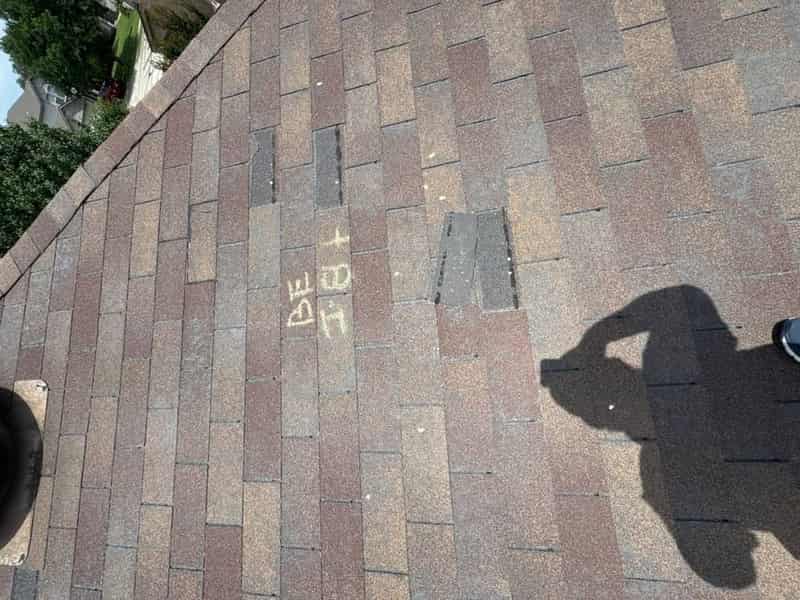
Hail damage that matters is usually invisible from the ground: bruising, where an impact fractured the mat under the granules; granule loss exposing the asphalt; split pipe boots; dented vents and flashing; shingles creased by wind. Dents in soft metal corroborate the date when the shingles are ambiguous. An honest inspection ends in one of three outcomes, and two of them are not a new roof.
- Repair. Isolated damage on a roof with life left in it, often below the deductible — your money either way, and cheaper paid directly.
- Replace. Damage across enough slopes, or a roof old enough, that patching is good money after bad. This is the case a claim exists for.
- Monitor. Nothing actionable today — the least profitable sentence in the trade, and one we say regularly.
Our own count, so you can weigh that last line: of the last 50 storm inspections we wrote up, 17 ended as repair, 20 as replace and 13 as monitor. Roughly one roof in four that we were called out to look at did not need work.
The storms are not hypothetical: NOAA's Storm Events Database logged 3.00-inch hail in Hays County on 9 May 2024, with 2.75-inch stones at Henly and 2.50-inch at Wimberley, and again at Leander on 16 May 2025. Point reports, not mapped paths — a reason to look at your roof, not proof that yours was hit.
What an inspection covers · Hail and wind damage
How long do I have to file a roof claim in Texas?
There is no single "you have X days to file" law in Texas. Two separate clocks apply, and they answer different questions.
1. Your policy's notice provision
Nearly every Texas homeowners policy requires notice of a loss promptly, or as soon as practicable. That is a term of your contract, not a statute — which is why no web page can tell you the number — and it is the deadline that bites, because a late report gives the carrier an argument that the delay damaged its investigation. Read your policy; if you cannot find the clause, ask your agent to point at it.
2. The legal deadline to sue your insurer
A limitations question, and not the same as when to report. A suit on a policy is a suit on a contract; Texas sets four years for the actions listed in Civil Practice and Remedies Code § 16.004, and a four-year residual period in § 16.051 for actions with no express period. But § 16.070 lets a contract shorten that: an agreement limiting the time to sue to less than two years is void in Texas, so two years is the floor a policy may write down to — and many do. That is where the "you have two years" you read elsewhere comes from: a common policy term, not a universal statute.
What to actually do: report promptly, in writing, and keep a copy. Do not wait for a contractor to tell you whether to file — document the roof first, then decide. Near a deadline, or already in a dispute, talk to a lawyer.
Once you file, your carrier is on a clock too
Insurance Code Chapter 542 sets deadlines running the other way: acknowledge the claim, begin investigating and request what it needs within 15 days; accept or reject in writing within 15 business days of receiving all of that, or say within the same period why it needs up to 45 days more; pay within five business days of saying it will. That clock does not start until you send what was asked for.
Who files the claim — you do
Insurance Code § 4102.163 is short, and it is why this page reads as it does. It provides that a contractor may not act as a public adjuster or advertise to adjust claims for any property for which the contractor is providing or may provide contracting services
— whether or not that contractor holds a public adjuster licence, and whether or not the homeowner signed a power of attorney. Added 2013, broadened 2019.
The Texas Department of Insurance publishes the conduct that crosses the line: offering to negotiate claim settlements or file a claim for the policyholder
, promising to recoverevery dime you are owed
, advertising to help homeowners avoid incorrect settlement pricing
, and telling anyone — including the insurance company — that you represent the policyholder or can speak for them on coverage. And it says so of websites: an advertisement includes a website.
So a company promising to manage the claim end to end is not making you a stronger offer. It is describing prohibited conduct, in the medium the rule names.
What the adjuster meeting is, and how to be ready
The adjuster is the carrier's representative. They will get on the roof or fly it, measure the slopes, count impacts inside test squares, decide which slopes they consider damaged and write a scope from that. What helps is boring: ladder access, an open attic, pets inside, your photo report in hand, your own notes on the day.
A contractor there helps: somebody who has already walked the roof can point at the boot or valley that is easy to miss from a ladder. That is a courtesy and nothing more — we do not represent you at that meeting or speak for you on coverage.
ACV, RCV and recoverable depreciation
TDI puts it plainly: replacement cost coverage pays to repair or replace at current prices; actual cash value pays replacement cost minus depreciation, the decrease in value from wear and age. TDI's example: a ten-year-old roof costing $10,000 to replace today, with a $2,000 deductible, pays $8,000 on replacement cost; on actual cash value the roof might be worth $7,000, so the same deductible leaves $5,000.
On a replacement cost policy the money arrives as two payments — TDI describes two checks, a partial one first and the rest after you have started work. The held-back amount is recoverable depreciation, released once the work is done and documented. One thing surprises people: § 707.004 lets an insurer refuse to release it until it has reasonable proof you paid your deductible — a cancelled check, money order receipt, credit card statement or executed installment plan. Which is why a contractor offering to make your deductible disappear is also offering to cost you that money.
Non-recoverable depreciation is never released: if your policy schedules the roof at actual cash value — common on older roofs, and something carriers add at renewal — that gap is yours. And a company will not pay for a new roof just because the old one is worn out.
Your deductible, including percentage wind and hail deductibles
Many Texas policies carry a separate wind and hail deductible, written as a percentage of the dwelling limit rather than a dollar amount. TDI's example, on a home insured for $150,000: a $500 deductible pays $6,000 of a $6,500 roof repair, while a 5 percent deductible — $7,500 — pays nothing, because the repair costs less.
Scale that to Central Texas replacement values. Illustrative only; your policy controls: on a $400,000 dwelling limit, 1 percent is $4,000 and 2 percent is $8,000. A homeowner who believes they have a $1,000 deductible and actually has a percentage one can file a claim that returns nothing. Read the declarations page rather than remembering it.
HB 2102: why no contractor can pay your deductible for you
Insurance Code § 707.002 requires a person insured under a property insurance policy to pay any deductible applicable to a first-party claim. Business and Commerce Code § 27.02 — rewritten by House Bill 2102 in 2019 — makes it an offence for a seller of goods or services to advertise, promise or actually pay, waive, absorb, rebate, credit, or in any other manner assist the insured in avoiding monetary payment of the required insurance deductible
, on work paid for out of a property insurance claim without the insurer's consent. Under § 27.02(d), that offence is a Class B misdemeanor. We state the classification because that is what the statute states; the punishment range sits elsewhere in Texas law, so ask a lawyer, not a roofer, what it comes to.
The same section requires the paperwork to say so. A contract reasonably expected to be paid wholly or partly from a property insurance claim, priced at $1,000 or more, must carry a specified notice in at least 12-point boldfaced type stating that Texas law requires you to pay your deductible and that it is a violation for the seller to knowingly let you avoid it. A claim-funded contract over $1,000 without that notice tells you something about the contractor.
So the pitch — nothing out of pocket, we will absorb the deductible — is not a discount. It is an offer to commit an offence, and a preview of how that company behaves when something goes wrong at your house. Report it: TDI directs violations to the Texas Attorney General.
What a supplement is — and what it is not
An approved scope is written from what one person saw in a couple of hours, so things get missed: a second layer found at tear-off, decking that fails when the old roof comes up, code items such as drip edge, ridge vent counted as ridge cap.
On our jobs, 82 percent of the first-round estimates we inherit from a carrier are missing at least one scope item. The three left off most often are decking, drip edge, and ice and water shield in the valleys. On homes built before about 2018 we usually find that none of the three was there to begin with, which is exactly when the code items matter.
The remedy is a supplement — those items documented and sent to the carrier with photographs, measurements and the code citation, so the estimate can be corrected against evidence. A document, not a negotiation, and the distinction is the whole point. We produce the record; you remain the one talking to your carrier.
The § 542A pre-suit notice, and why you keep every document
If a dispute reaches a lawsuit, Insurance Code Chapter 542A adds a step first. Under § 542A.003, not later than the 61st day before filing an action, the claimant must give written notice stating the acts or omissions giving rise to the claim, the specific amount alleged to be owed, and the attorney's fees incurred so far. The exceptions are narrow — among them, too little time left before limitations expires, or a counterclaim.
Nobody builds that notice from memory. Every element is easier if you kept the dated photo report, the claim number, the adjuster's estimate, the emails and the invoices — which is what we mean by keeping the record. Whether to send one is a question for a lawyer.
What if the claim is denied, or the number is too low?
A denial has to come with a reason. TDI states that if the company rejects your claim, it must say why in writing, so ask for that letter before you do anything else. If the claim is accepted but the scope is short, the first move is the supplement described above: the missing items, photographed and measured, sent back with the code citation. Most shortfalls end there.
If they do not, your policy gives you a formal route that does not need a lawyer: appraisal. TDI describes it plainly. You and the insurance company each hire an appraiser, the two appraisers choose a third as an umpire, and the umpire's decision is binding on both sides on the amount of the damage. You pay your own appraiser and half of the umpire's fee, so it makes sense on a whole-roof disagreement and not on a $900 gap. Appraisal settles how much, not whether the loss is covered.
Beyond that, TDI lists three more doors. Some homeowners hire a public adjuster, who charges a fee and is licensed to negotiate for you; a roofing contractor cannot be one on a roof it may work on, which is why we do not. You can file a complaint with TDI if you think the company has treated you unfairly. And you have the right to sue, or to ask for mediation instead of court. A suit on the policy runs into the 60-day pre-suit notice described above, and the record you kept is what that notice is built from.
When it is not worth filing
Nobody in this trade writes this section, so here it is. If the damage is under your deductible, or close to it, a claim can cost more than it returns — TDI notes that filing small claims may affect what you pay for insurance later, and a claim on a roof that will not total leaves you the paperwork, the claim history and the bill anyway.
Document the roof, get a repair number, compare it with the deductible on the declarations page, then decide. If the answer is not to file, we will say so — and you keep the report.
Class 4 impact-resistant shingles and premium credits
A Class 4 shingle is the top rating in the standard impact test for roof coverings, and a sound choice in a hail belt. On insurance, hedge with us: TDI lists an impact-resistant roof among discounts a company may offer, and says each company decides which discounts it offers and what they are worth. So a credit is commonly available, and the amount is your carrier's to set. Ask your agent before you pay for the upgrade. We install Class 4 products and price them beside the standard option. More on asphalt shingles and Class 4.
What Waypoint does — and does not do
You file your own claim; we inspect and document; we meet your adjuster on site if you invite us; we build to the approved scope and supplement with evidence when the scope is short; we do not promise an outcome, and Texas law forbids waiving your deductible.
Waypoint does
- Climb and inspect the roof, free, and say when it does not need work
- Photograph the damage and give you the report to keep
- Meet your adjuster on the roof, if you invite us
- Build to the approved scope
- Supplement with evidence when the scope is short
- Take no deposit — you pay when the work is finished
Waypoint does not
- File the claim for you
- Negotiate your settlement or speak for you on coverage
- Act or advertise as a public adjuster (Tex. Ins. Code § 4102.163)
- Promise an outcome, a decision, or a roof at no cost
- Pay, absorb or rebate your deductible (Tex. Bus. & Com. Code § 27.02)
HAAG certification is a credential in inspection and damage assessment, and that is all we claim it for: our documentation is produced to the standard the industry trains adjusters to. It does not mean we assess your claim or price your loss.
Does Texas homeowners insurance cover hail damage to a roof?
A standard Texas homeowners policy generally covers sudden windstorm and hail damage, minus your deductible. What varies — and what decides the money — is replacement cost versus actual cash value, and the wind and hail deductible. Both are on your declarations page.
Will insurance pay for a new roof after hail in Texas?
Sometimes. It depends on how much of the roof is damaged, what your policy covers and what the adjuster documents — and no roofer can tell you in advance. Anyone quoting odds is guessing at a decision on a roof they have not seen.
Can a roofer negotiate with my insurance company in Texas?
No. Under Insurance Code § 4102.163 a contractor may not act as a public adjuster or advertise to adjust claims for property it may work on, and TDI names offering to negotiate settlements as prohibited conduct. What a roofer may do: inspect, document, meet the adjuster on site, build the approved scope, supplement with evidence.
Should I get an inspection before I file a claim?
We think so, and it costs nothing. Filing is a decision about money, and you cannot make it before you know whether the roof needs a repair, a replacement or nothing. A dated report also puts the roof's condition that day on the record.
What happens if the adjuster's scope is less than the roof needs?
That is what a supplement is for: missing items documented with photographs, measurements and code citations, sent so the estimate can be corrected. Some are accepted, some are not. If a real dispute remains, that is where Chapter 542A and a lawyer come in.
Will my premium go up if I file a hail claim?
It might, and it is carrier-specific — your agent is the only person who can answer it for your policy. TDI states generally that filing small claims may affect what you pay for insurance later, which is why "is it worth filing" deserves a real answer first.
A roofer knocked on my door and offered to cover my deductible. Is that legal?
No. Business and Commerce Code § 27.02 makes it an offence to advertise or promise to pay, absorb or rebate a policyholder's deductible on work funded by a property insurance claim, and that offence is a Class B misdemeanor. Do not sign at the door, and check that any claim-funded contract over $1,000 carries the 12-point boldfaced notice.
Do you charge for a storm inspection?
No. The inspection and the photo report are free, and the report is yours whether or not you hire us or file anything. No deposit either: you pay when the work is done. Roof replacement · See our work · Contact us
Do I have to use the roofer my insurance company recommends?
We have not found a Texas statute or TDI guidance that lets a homeowners carrier require a particular roofer. Your policy is the contract; if an adjuster says you must use a network contractor, ask where the policy says so. Carriers may suggest a program contractor, and you may take the suggestion or not. What the policy does control is the amount it pays, which is why a scope written from one adjuster's visit still needs the supplement process whoever builds the roof.
Do I need more than one estimate?
No law requires it. TDI does recommend it: get estimates from more than one contractor, and show them the insurance company's estimate. We think that is good advice, and we give you our number and the photo report to take to anyone else you like.
Can I keep the claim money and not replace the roof?
The first check is yours. TDI explains that the first payment arrives after the adjuster has looked at the damage, for the estimated cost of repairs minus depreciation and your deductible. The held-back depreciation is a different matter: the company gives you the check for the amount it kept for depreciation after it gets the bill for the finished job, and § 707.004 lets it wait for proof you paid your deductible. So on a replacement cost policy, not doing the work forfeits the second payment. Whether an unrepaired roof affects your renewal is a question for your agent, not for us.
Why is my mortgage company's name on the check?
Because the house is their collateral. TDI: if you owe money on your home, the insurance company will make the check for repairs out to both you and your mortgage company. The servicer will ask for paperwork, usually the adjuster's estimate, the contract and proof the work is progressing, and after the mortgage company gets the information, it must release all or some of the money to you within 10 days. Ask your servicer for its claim-funds checklist the day the check arrives, not the day the roofer needs paying.
Does a hail claim go on my record?
Yes. TDI: a CLUE report shows the claims filed for any house or car for the past seven years, and insurance companies look at a property's past claims and use that as a factor in deciding how much you'll pay for homeowners insurance. That is the other reason the "when it is not worth filing" section exists. A claim that returns nothing still sits on that report.